
How to Dispute Credit Report Errors for Free: A US Step-by-Step Guide
Find and fix inaccurate credit report entries for free with a bureau-by-bureau checklist, evidence matrix, letter template and dispute tracking plan.
Contents
- The five-minute action plan
- Step 1: Get the right report without paying
- Step 2: Decide whether the item is actually wrong
- A crucial distinction: inaccurate reporting versus a billing dispute
- Step 3: Build an evidence packet that answers the exact question
- Example: a late payment reported despite an on-time payment
- Example: balance differences that are not necessarily errors
- Step 4: File with the credit bureau reporting the error
- A reusable dispute letter with evidence mapping
- Step 5: Also dispute with the company that furnished the data
- Step 6: Track the investigation without confusing the deadlines
- What the result actually means
- If your dispute is rejected: a decision tree
- If the account is not yours: treat it as potential identity theft
- How to avoid credit-repair scams
- Three practical scenarios and what makes them different
- Scenario A: one incorrect late payment, one bureau
- Scenario B: duplicate collection at two bureaus
- Scenario C: an unfamiliar account appears everywhere
- How to check whether the correction actually worked
- Official sources and next steps
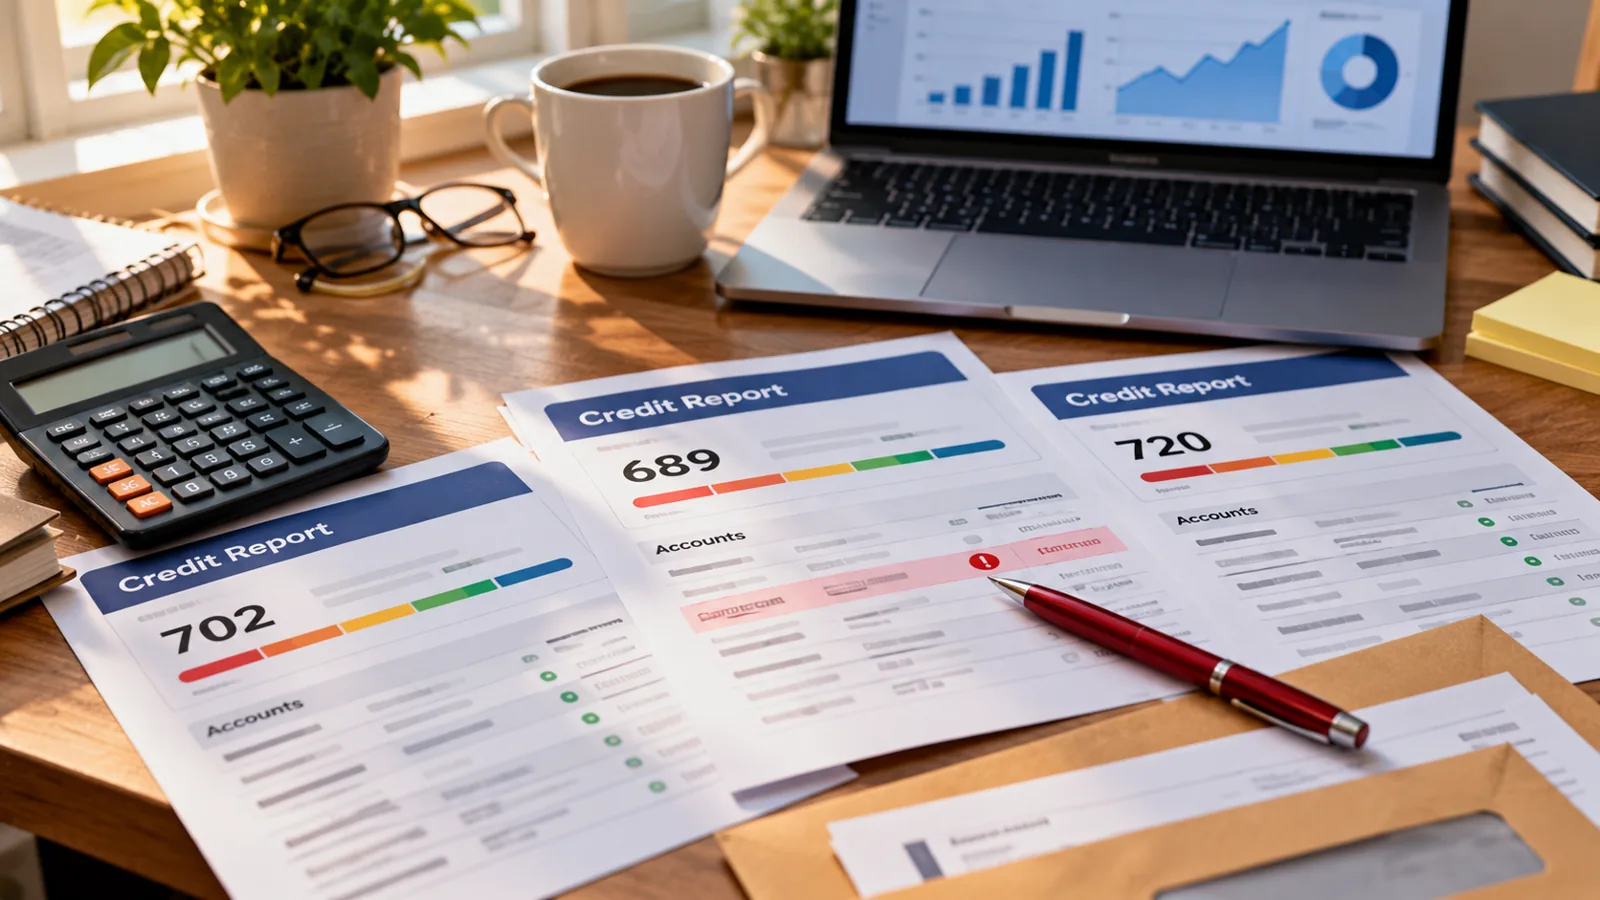
A credit report error can make a loan application harder, increase borrowing costs, or create confusion about accounts you never opened. You can dispute inaccurate or incomplete information on your US credit reports for free. The most reliable approach is to identify exactly which bureau reports the error, collect records that prove the specific fact, dispute with that bureau, and separately contact the company that supplied the data. Do not pay a credit-repair company just to exercise these rights. This guide includes a practical evidence matrix, a dispute-letter template, a 45-day tracking plan, and separate routes for identity theft and billing disputes.
This is general US consumer information, not individualized legal advice. Procedures and outcomes depend on the facts; filing a dispute does not guarantee a deletion or a higher credit score. Official starting point: Consumer Financial Protection Bureau (CFPB), reviewed September 2026.
The five-minute action plan
- Download your reports from all three bureaus using AnnualCreditReport.com; save each report privately.
- Mark the exact account, date, balance, status, inquiry, or identity detail you believe is wrong.
- Find independent supporting records and write a one-sentence explanation of the mismatch.
- Dispute with every bureau displaying the error, then notify the furnisher—the bank, lender, collector, or other reporting company.
- Record submission dates, confirmation numbers, deadlines, and results; recheck the updated reports.
Step 1: Get the right report without paying
AnnualCreditReport.com is the federally authorized central source for reports from Equifax, Experian and TransUnion. The three nationwide bureaus continue to offer free weekly online reports through this service. You are requesting credit reports, not necessarily credit scores; a score shown by an app can use different data or a different scoring model. The FTC explains the weekly program and why reviewing reports can reveal identity theft: FTC guide to disputing errors.
Check each bureau separately. A lender may report to one, two, or all three. A mistake on TransUnion is not automatically a mistake on Equifax. Save a dated PDF or printed copy if available, but store it securely because credit reports contain sensitive identifying information. Never email an unredacted full report to an unfamiliar service.
Step 2: Decide whether the item is actually wrong
An unexpected negative entry is not automatically inaccurate. A late payment that really occurred may be reportable even if it lowers your score. A legitimate account may appear under a bank’s unfamiliar legal name. Investigate before disputing. For older adverse information, reporting time limits and exceptions can be complicated; do not assume that paying a debt restarts or removes every reporting entry.
| Report entry | Check against | Useful supporting evidence |
|---|---|---|
| Payment marked late | Due date, grace period, posting date, payment history | Bank statement, confirmation number, lender ledger |
| Wrong balance or credit limit | Statement closing date and reported date | Dated statement showing correct figure |
| Account you never opened | Creditor name, account opening date, identity-theft signs | Identity Theft Report and correspondence |
| Account shown open after closure | Closure date and remaining balance | Closure letter and final statement |
| Duplicate collection | Account identifiers and ownership | Collector notices, account statements |
| Incorrect personal information | Names, addresses, date of birth | Appropriate identity or address documents |
| Inquiry you do not recognize | Company, date, permissible purpose | Application records and company response |
A crucial distinction: inaccurate reporting versus a billing dispute
A credit-report dispute concerns what a credit reporting agency says about an account. A credit-card billing dispute challenges a charge or billing error with the card issuer and may have separate deadlines and procedures under the Fair Credit Billing Act. If an unauthorized charge caused an incorrect reported balance, you may need to pursue both processes, not substitute one for the other. See the FTC explanation of credit-card billing disputes.
Step 3: Build an evidence packet that answers the exact question
A dispute saying “this is wrong” gives an investigator little to verify. A stronger packet states the specific field, the reported value, the correct value, the reporting date, and why a particular document proves the difference. Label your exhibits A, B and C. Provide copies, never originals, and redact unrelated account numbers when allowed by the submission instructions. Keep enough identifying information for the bureau to locate your file.
Example: a late payment reported despite an on-time payment
Imagine a card issuer reports a 30-day late payment for March, but your bank statement shows an electronic payment cleared before the contractual due date. First compare the payment received date with the bank debit date; they are not always identical. Obtain the card issuer’s payment confirmation or transaction history. Then dispute the late-payment status and identify the precise month. This is a hypothetical example, not an account we tested.
Example: balance differences that are not necessarily errors
Suppose a credit card currently shows $600 in its app while the credit report shows $1,200. The report may reflect an earlier statement-closing date. Compare the dates before filing. If the reported amount matches the actual balance on the reporting date, the discrepancy may simply be timing. A strong dispute explains the mismatch at the same point in time, rather than comparing today’s live balance with last month’s snapshot.
Step 4: File with the credit bureau reporting the error
Use the bureau’s official dispute portal or its verified mailing instructions. Online submission can be convenient and generates a tracking number; certified mail with return receipt can provide a paper trail. The FTC provides official mail-address guidance, but addresses may change, so verify the current instructions on the bureau’s own website before posting sensitive records: FTC dispute process.
For each disputed item, specify whether you want the bureau to correct a field or delete an item that does not belong to you or cannot be verified. Upload only the evidence relevant to that claim. Keep the confirmation screen or a copy of the signed letter and proof of delivery.
A reusable dispute letter with evidence mapping
Adapt this template to your facts. Do not include an invented allegation, and do not send a full Social Security number unless the verified recipient specifically requires it through a secure process.
[Date] [Full name and mailing address] [Credit bureau and verified dispute address] Re: Dispute of inaccurate information on my credit report I dispute the following information in my [bureau name] report dated [date]: Furnisher/account: [company and last four digits] Reported information: [specific field and reported value] Correct information: [specific field and correct value] Reason: [brief factual explanation] Please investigate and correct or remove this inaccurate information. Attached copies: Exhibit A [description]; Exhibit B [description]. Please send the investigation results and an updated report if the information changes. Sincerely, [Name]This is an original practical adaptation; compare it with the FTC sample letter before submitting.
Step 5: Also dispute with the company that furnished the data
The credit bureau and the furnisher have distinct roles. The bureau investigates information on its file, while the furnisher can inspect the underlying account records and correct its reporting. The CFPB recommends contacting both. Send the furnisher a concise written dispute using its designated dispute address, with the same account-specific evidence and a request to correct reporting to every bureau that received the wrong data. A customer-service chat is useful for finding records but should not replace the formal dispute route when the issue remains unresolved.
Under the CFPB’s guidance, furnishers generally must investigate and respond within 30 days after receiving a direct dispute, subject to applicable rules and exceptions. Read CFPB instructions for the current process.
Step 6: Track the investigation without confusing the deadlines
Credit reporting agencies generally have 30 days to investigate, but some disputes can take up to 45 days, including specified situations involving free annual reports or additional information submitted during the investigation. They generally have five business days after completing the investigation to notify you of the result. These are legal timeframes, not promises that every complex problem will be fully resolved by day 30. CFPB investigation timing.
| When | What to record | What not to assume |
|---|---|---|
| Day 0 | Bureau, disputed item, submission method, receipt evidence | The clock necessarily started when you drafted the letter |
| Days 1–7 | Acknowledgment and tracking number | An automated acknowledgment means the item was verified |
| Around day 30 | Investigation status and any requests for evidence | Every dispute must finish in exactly 30 calendar days |
| Up to day 45 where applicable | Check the applicable extension and updated response | An extension applies automatically to every case |
| After result | Save outcome, compare each bureau report, check furnisher updates | A corrected entry must immediately raise your credit score |
What the result actually means
- Corrected: confirm the field now matches the supporting evidence and check all affected reports.
- Deleted: save the outcome and continue monitoring; deletion does not by itself prove fraud or wrongdoing.
- Verified as accurate: read the explanation, check whether the bureau investigated the precise disputed field, and consider additional relevant evidence.
- Frivolous or irrelevant: the bureau may decline to investigate an inadequately specified or repetitive dispute; the CFPB explains the notice requirement.
- Reappeared: document the date and contact the bureau promptly; additional reinsertion protections may apply under federal law.
If your dispute is rejected: a decision tree
| Situation | First next action | Potential escalation |
|---|---|---|
| New records prove the bureau missed a key fact | Submit a focused new dispute with genuinely new evidence | CFPB complaint if unresolved |
| Creditor confirms its own record is wrong | Request written correction and reporting update | Contact bureau with creditor confirmation |
| You suspect identity theft | Use IdentityTheft.gov and consider fraud alerts or freezes | Identity-theft blocking process |
| Accurate but unfavorable information | Do not label it an error | Consider payment or budgeting options |
| The investigation is completed but you disagree | Request clarification and consider a consumer statement | CFPB complaint or qualified legal advice |
A CFPB complaint is not a shortcut around an ongoing dispute. The CFPB’s complaint portal provides eligibility and timing instructions; preserve the bureau’s completed response and your evidence before escalating. Start at CFPB complaint portal. In complicated cases involving damages, mixed credit files, repeated reinsertion, or an imminent mortgage closing, a qualified consumer-law attorney may be appropriate.
If the account is not yours: treat it as potential identity theft
An unfamiliar account could be a data-matching error, but it may also indicate someone used your identity. If you have reason to suspect fraud, do not rely on an ordinary accuracy dispute alone. Visit IdentityTheft.gov for an Identity Theft Report and recovery plan, consider a free credit freeze with each nationwide bureau, and contact the creditor’s fraud department through independently verified contact details. The FTC explains that identity-theft-related information can qualify for a special blocking process when the statutory requirements are met.
A credit freeze restricts access to your credit file for many new-credit decisions; a fraud alert asks businesses to take additional identity-verification steps. Neither fixes an already inaccurate account by itself. Keep the dispute, fraud response and security steps distinct.
How to avoid credit-repair scams
You do not have to pay anyone to dispute a credit report error. Be wary of services promising guaranteed deletion of accurate negative information, demanding advance payment, asking you to invent identity theft, or insisting that you never contact the bureaus yourself. Accurate negative information generally cannot be removed merely because it is inconvenient. See FTC credit-repair warning.
Three practical scenarios and what makes them different
Scenario A: one incorrect late payment, one bureau
A borrower spots a May late-payment mark only on Experian. They retrieve the May payment receipt and issuer account history, dispute the specific May status with Experian, and send the same evidence to the issuer. They do not open unnecessary disputes at bureaus that do not display the mark. They save both confirmation numbers and check the updated Experian report after the result.
Scenario B: duplicate collection at two bureaus
A collection appears twice under two agency names. The consumer first determines whether these are truly duplicate reports of one debt or separate legitimate entries with different account histories. They gather the original creditor and collection notices, identify exactly which information is inaccurate, then file targeted disputes with each affected bureau and furnishers. They avoid claiming every pair of similar names is automatically illegal duplication.
Scenario C: an unfamiliar account appears everywhere
A consumer finds a newly opened account on all three reports that they never authorized. They document the entry, contact the creditor’s fraud unit, use IdentityTheft.gov, consider freezes, and pursue the appropriate credit-file dispute or identity-theft block with each bureau. They avoid sending sensitive documents through links received in unsolicited texts or emails.
How to check whether the correction actually worked
After receiving a result, compare the updated field—not just a headline saying “resolved”—against your original report and exhibits. Note whether the status, balance, delinquency month, account ownership or inquiry was corrected. Recheck the other bureaus if the furnisher said it updated all of them. Your credit score may not change, may change later, or may change for other reasons; scores depend on the full file and model. Keep a secure folder with the original report, letters, submission receipts, investigation notices and final corrected reports.
Official sources and next steps
- CFPB: dispute instructions (reviewed September 2026)
- CFPB: investigation deadlines
- FTC: how to dispute errors and contact furnishers
- FTC: sample dispute letter
- AnnualCreditReport.com: free reports
- IdentityTheft.gov: identity theft recovery
Bottom line: the most effective free credit-report dispute is specific, documented, and tracked. Get all three reports, identify the exact false statement, support it with dated records, contact the affected bureau and furnisher, and verify the outcome. If an account may be fraudulent, protect your identity in parallel rather than waiting for an ordinary dispute to finish.
You may also like
 Technology & How-To
NHS App Prescription Not Showing? Check GP Approval, Pharmacy Status and Tracking
Find out why a prescription or medicine is missing from the NHS App in England. Separate repeat requests,…
 Technology & How-To
Google Wallet Not Working After Switching Phones? Fix Card Setup and Tap to Pay
Google Wallet transferred but tap to pay fails? Separate card verification, bank approval, NFC, screen lock and device…
 Technology & How-To
iCloud Family Sharing Not Working? Why You Still See 5GB and How to Fix It
Still seeing 5GB after joining an iCloud family plan? Check the account, invitation, sharing settings, personal plan and…