
Lloyds Bank Branch Closures 2026–2027: November List, Dates and Banking Alternatives
Lloyds November 2026 closures: verify dates for 10 branches, find open alternatives, understand Post Office and Banking Hub services, cash access rights and limits.
Contents
- Lloyds Bank branch closures in November 2026: verified list
- What happens to your Lloyds account when your local branch closes?
- The most easily missed risk: another nearby branch may also be closing
- Where can you bank after your Lloyds branch closes?
- How to find the nearest working alternative: illustrated walk-through
- Step 1 — Look up the closing branch and read the notice
- Step 2 — Decide what you need, before you choose a map pin
- Step 3 — Search across other branches and cash services
- Step 4 — Check the Banking Hub timetable, not just its location
- Step 5 — Verify the new location again immediately before travelling
- A verified local example: Accrington and its alternatives
- What the branch review data really shows — and what it does not
- Post Office banking: exact tasks, documents and limits
- PayPoint cash deposits: why app deposits and card deposits are not interchangeable
- A practical decision table for real households and businesses
- Three worked scenarios the typical closures list does not solve
- Scenario A — Cash deposits for a small shop
- Scenario B — Older customer without smartphone access
- Scenario C — Huyton customer tries a sister-brand branch
- Do FCA rules stop Lloyds from closing a branch?
- How to request a local cash-access review or challenge an assessment
- The difference between an ATM, a Banking Hub and a full service branch
- Accessibility and digital exclusion: what customers can ask for
- What if the branch cash machine also closes?
- Do you need to switch banks? Usually not — but you may choose to
- Practical checklist: do this before your branch closes
- Scams to avoid during a branch closure
- Why our November list is narrower than some “full list” headlines
- Sources and editorial verification
Last verified: 27 October 2026 (UK). This is a rolling, evidence-linked guide to announced Lloyds Bank branch closures. Plans and local services may change before a closure date. Always recheck the bank’s live branch listing before travelling.
Quick answer: Lloyds has published closure notices for 10 branches in November 2026: Accrington, Wallsend, Ilkeston, Willenhall, Leicester Melton Road, Huyton, Wakefield, Wigston Magna, Worksop and Harrogate. The final announced date in this November group is 19 November. If your branch is affected, you usually do not need to switch your current account: identify an appropriate Lloyds, Halifax or Bank of Scotland branch, Post Office, Banking Hub or other cash service before the old branch closes. Not all alternatives provide every service.
This article goes beyond closure headlines: every location below links to a bank-operated branch notice; we explain how to avoid a soon-to-close “replacement” branch, show what different services actually do, and offer checklists for cash-dependent households, small businesses and customers needing face-to-face help. It also distinguishes regulatory protections for access to cash from the right to a full-service bank branch.
Lloyds Bank branch closures in November 2026: verified list
The table covers Lloyds Bank-branded branches in the November wave, not every Lloyds Banking Group closure and not the full 2026–27 programme. Each date below was checked against its official Lloyds branch page, rather than taken solely from press roundups. For later additions or changes, use the bank’s official branch closures directory.
| Branch / area | Full address | Closure date | Official confirmation |
|---|---|---|---|
| Accrington (Lancashire) | 2 Peel Street, BB5 1EP | 03 Nov 2026 | Lloyds notice |
| Wallsend (Tyne and Wear) | Royal Chambers, High Street East, NE28 8PJ | 03 Nov 2026 | Lloyds notice |
| Ilkeston (Derbyshire) | Market Place, DE7 8GS | 05 Nov 2026 | Lloyds notice |
| Willenhall (West Midlands) | Market Place, WV13 2AE | 05 Nov 2026 | Lloyds notice |
| Leicester Melton Road (Leicestershire) | 184 Melton Road, LE4 5EE | 09 Nov 2026 | Lloyds notice |
| Huyton (Liverpool) (Merseyside) | 14–16 Sherborne Square, L36 9UR | 09 Nov 2026 | Lloyds notice |
| Wakefield (West Yorkshire) | 17 Westgate, WF1 1JZ | 10 Nov 2026 | Lloyds notice |
| Wigston Magna (Leicestershire) | 61 Leicester Road, LE18 1NR | 11 Nov 2026 | Lloyds notice |
| Worksop (Nottinghamshire) | 65 Bridge Street, S80 1DH | 11 Nov 2026 | Lloyds notice |
| Harrogate (North Yorkshire) | 8–11 Cambridge Crescent, HG1 1PQ | 19 Nov 2026 | Lloyds notice |
Important distinctions: A closure date is not necessarily the last day a particular counter is open for a given service: opening hours, holidays and appointment availability differ. Some associated cash machines also have separate permanent closure notices. Never assume an ATM remains after the branch shutters.
These ten closures have been widely reported, including by Eastern Eye and other coverage. Long running trackers, such as MoneySavingExpert, span multiple Lloyds, Halifax and Bank of Scotland closures, so totals may differ because of brand, period and whether already-closed branches are included. Avoid comparing headline counts without checking those definitions.
What happens to your Lloyds account when your local branch closes?
The closure of a physical Lloyds branch does not itself close your bank account, cancel your debit card or require you to switch providers. Your account can continue to be managed through suitable online, telephone and in-person channels. The change is about where services are delivered. That matters because a service that sounds like a substitute in a press release may not be suitable for a particular person or transaction.
For example, someone who needs to withdraw £40 can often use a free ATM. Someone paying in £2,000 in business takings, needing change for a till or resolving a disputed transaction may need a substantially different channel. A relative handling an account for a person who cannot manage digital banking may need specialist authority, not merely the nearest counter.
The most easily missed risk: another nearby branch may also be closing
Huyton is a useful real-world warning. Lloyds Huyton at 14–16 Sherborne Square is scheduled to close on 9 November 2026. The local Halifax Huyton branch at 55 Derby Road is separately scheduled to close on 4 November 2026. Both dates are published on their respective bank-operated branch pages. A customer who sees “Halifax is part of Lloyds Banking Group” and plans to use that Halifax after 9 November could find it already shut.
Before choosing a substitute, compare (1) the specific building and address, (2) the relevant brand and your account eligibility, (3) its own closure notice and opening hours, and (4) whether it actually performs your transaction. Use the live multi-brand branch finder rather than saving an undated list.
Where can you bank after your Lloyds branch closes?
The bank lists several routes, each with different strengths and limits. The diagram below is an independently designed reference guide based on official instructions—not a screenshot of a Lloyds, LINK or Post Office website.
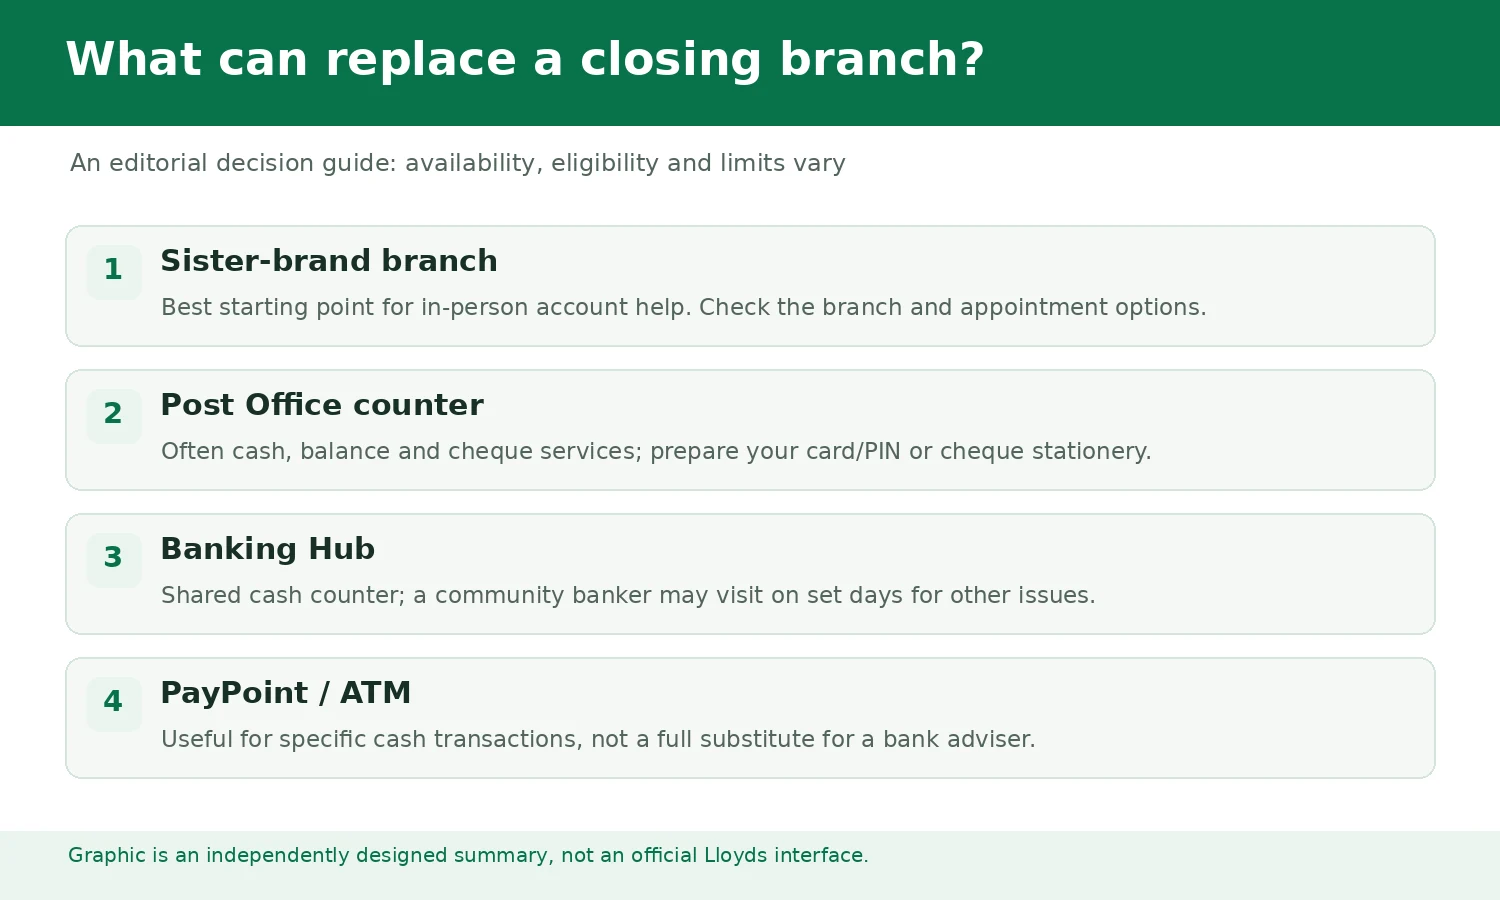
| Service | Cash withdrawal | Deposit notes/coins | Deposit cheques | Detailed account help |
|---|---|---|---|---|
| Lloyds / Halifax / Bank of Scotland branch | Usually yes; check services | Usually yes; check branch | Usually yes; check branch | Usually, depending on service and appointments |
| Post Office | Yes on eligible cards; limits apply | Many branches, with bank/branch limits | Specific stationery and eligibility; check first | No full Lloyds adviser |
| Banking Hub | Counter service while open | Counter services; bank conditions apply | Often possible; check | Only on scheduled community banker days |
| PayPoint | Not a standard cash withdrawal service | Eligible personal-account deposits at participating shops | Not the standard cheque option | No account adviser |
| ATM | Yes if available, possibly free or fee-charging | Only if machine supports deposits | No | No |
How to find the nearest working alternative: illustrated walk-through
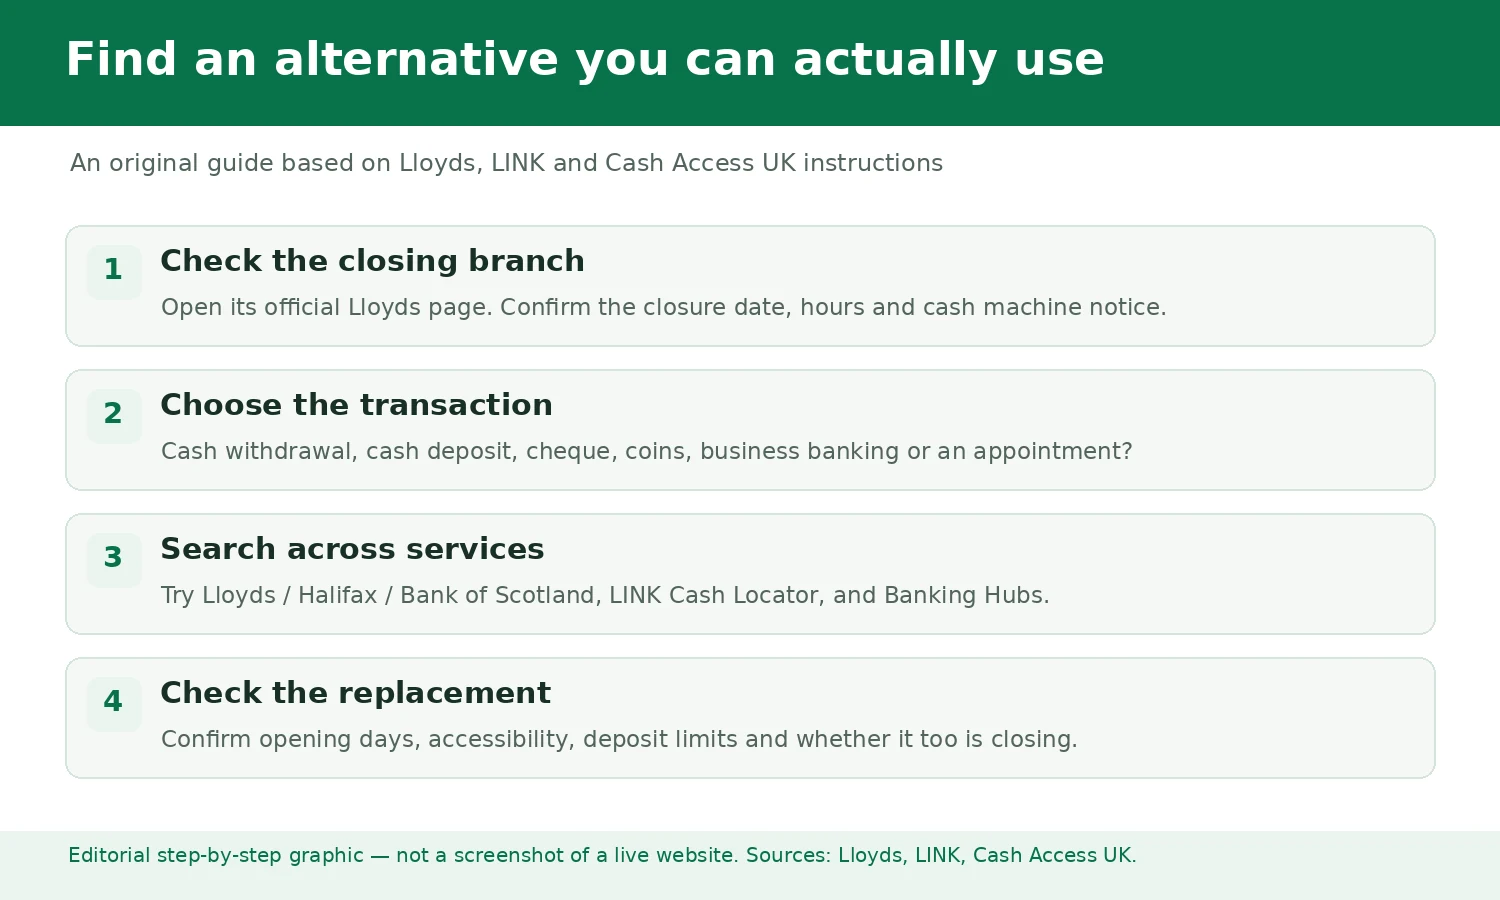
Step 1 — Look up the closing branch and read the notice
Open the Lloyds location directory and enter your town or postcode, such as BB5 1EP for Accrington or NE28 8PJ for Wallsend. Open the exact bank branch listing and inspect the banner mentioning a permanent closure. Check the branch’s accessibility options and cashpoint notice separately. If you are looking at an old search result, verify it against the page itself.
Step 2 — Decide what you need, before you choose a map pin
Write down your transaction: cash in or out, coins/change, cheque, paper statement, balance enquiry, card problem, identity verification, complex account assistance or business depositing. Ask whether you need counter staff or whether a machine can do the job. Searching only for “nearest bank” can return a location that lacks the facility you need.
Step 3 — Search across other branches and cash services
Try Lloyds’ co-servicing explanation and other Lloyds, Halifax or Bank of Scotland locations for eligible personal-account transactions. For cash access, use LINK Cash Locator and search by town or postcode. Its filters let you request services such as withdrawing notes, depositing notes or coins, free-to-use access, wheelchair accessibility and hearing loops; selecting Post Offices alongside a bank brand may reveal more usable options.
Step 4 — Check the Banking Hub timetable, not just its location
A Cash Access UK Banking Hub generally has a shared Post Office-operated cash counter Monday–Friday, 9am–5pm. But a community banker from your own bank attends only on a designated day at participating hubs. If you need help with account documents, payments or a complicated query, consult the hub’s specific schedule and contact the bank before making a trip. A shared cash counter is not equivalent to a bank adviser being available every day.
Step 5 — Verify the new location again immediately before travelling
Double-check opening hours, whether the ATM is still operating, whether the service supports personal or business accounts, and what ID/card/PIN or deposit stationery you must bring. If you are travelling with mobility limitations, inspect the specific accessibility facilities; a service being geographically nearby does not necessarily mean it is reachable or usable.
A verified local example: Accrington and its alternatives
Lloyds’ Accrington Closing Branch Review, Part 1 (PDF) documents the bank’s own stated alternatives, making it particularly useful for readers who want evidence rather than generic advice. It confirms the 3 November 2026 closure at 2 Peel Street and names Halifax, 9 Union Street, Accrington BB5 1LF as a nearby alternative branch. It also lists a Great Harwood Banking Hub, 14 Queen Street, BB6 7QQ and Accrington Post Office, 18 Abbey Street, BB5 1EB. These are named in the published review; present-day opening hours and each service’s eligibility must still be checked independently.
The same review says its on-site cash machine will also close, and identifies a free-to-use alternative at the nearby Halifax branch. This detail matters: a reader who assumes the old Lloyds ATM will stay available could arrive after the closure and find no machine. View the bank’s original closure report for the address list and branch-specific analysis.
What the branch review data really shows — and what it does not
The official Accrington review provides a rare source of branch-specific evidence. It says 641 customers transacted at the counter or immediate deposit machine in at least four of six months ending February 2026. It also reports 20% of personal customers using the branch were aged 75 or over, and 7% of customers using it were business customers. These are the bank’s stated measures for this branch—not representative UK national estimates and not predictions of who will be unable to bank after closure.
The useful insight is not merely the size of the numbers. Regular counter usage points to a segment with repeated in-person needs, while the age profile signals why travel and accessible alternatives merit attention. A closure report often contains several metrics with different populations and reference periods. For this reason, it is misleading to treat every percentage in the report as the share of all local residents, or to claim those numbers prove that specific customers cannot use online banking.
Post Office banking: exact tasks, documents and limits
Lloyds explains that eligible personal customers can use the Post Office for cash payments, balance checks, cash withdrawals and some cheque deposits. The standard bank guidance gives free withdrawals of up to £300 per day at the Post Office with a debit card and PIN. It also publishes a cash-deposit allowance of £2,995 per month and £20,000 per year for the relevant personal-account service, although branch-specific, account and channel rules can differ. Check the current Lloyds Post Office page for live restrictions before depositing money.
Cheque deposits deserve extra attention. Lloyds’ cheque deposit instructions describe the need for a specific cheque envelope and pre-printed paying-in slip. Meanwhile, wording in an individual branch closure review may say cheques are not accepted at a particular Post Office alternative. That apparent mismatch is a warning against assuming every Post Office handles every banking task in precisely the same way. Check the participating branch and your bank’s current requirements, and do not put cash into a cheque-only envelope.
- For cash: take your eligible debit card, know your PIN, and ask about denomination or local deposit restrictions before bringing a large sum.
- For cheques: prepare the specific deposit slip and envelope required for your product; verify the Post Office actually provides the service.
- Keep a transaction receipt and check the expected credit time. The processing time for cheques may differ from cash.
- If you need a personal appointment, complex account assistance or specialist documents, choose a bank branch or scheduled community banker instead.
PayPoint cash deposits: why app deposits and card deposits are not interchangeable
Lloyds distinguishes between using the mobile app barcode at a participating PayPoint and using an eligible debit card/PIN at supported stores. For the app-barcode route, the published limits include £300 a day and £600 a month, and the barcode is single-use with a short validity period. Lloyds separately describes debit-card deposits with a £300 per-transaction limit and broader eligible monthly and annual limits. These limits are not necessarily interchangeable; the feature may be restricted to personal customers and a particular store’s equipment.
Example: a person who receives £700 in cash on one day cannot simply split it into three app-barcode deposits at three different shops and assume that is within the bank’s rules. They should use the current official PayPoint instructions to determine the channel, limits, account eligibility and a suitable alternative.
A practical decision table for real households and businesses
| Situation | First choice to investigate | What to confirm |
|---|---|---|
| Pensioner withdraws small amounts weekly | Free ATM or Post Office | Physical access, cash availability, fees, PIN/card support |
| Cash-heavy shop takes £1,200 daily | Business-compatible branch or hub | Business account, deposit volume, fees, notes/coins, timing |
| Customer receives an occasional cheque | App cheque deposit or compatible Post Office | Value limit, cheque type, deposit slip/envelope |
| Customer needs account review or documents | Full-service branch or community banker | Appointments, ID requirements, specialist availability |
| Person uses wheelchair and needs staff | Accessible branch / hub / Post Office | Level access, accessible counter, travel connections |
| Business needs till change | Banking Hub or designated branch | Change-giving availability and business restrictions |
Three worked scenarios the typical closures list does not solve
Scenario A — Cash deposits for a small shop
A shop owner takes £900 in notes and coins after a weekend. The nearest cashpoint is not necessarily a deposit machine, and a personal PayPoint feature is not a substitute for a business deposit facility. The owner should check Lloyds’ business in-person banking guidance, identify an eligible Post Office or Banking Hub and confirm cash limits, coin handling, costs and when the deposited money becomes available. Where regular deposits exceed a retail outlet’s thresholds, a sustainable plan may require a different branch or an appropriate business service.
Scenario B — Older customer without smartphone access
An older customer in Accrington who regularly uses the counter can first check whether Halifax 9 Union Street offers the exact transactions they need. If they have accessibility requirements, verify level access, opening days and local transport. Lloyds’ closure report also identifies a Great Harwood Banking Hub; a companion should not assume the bank’s community banker attends every day. Requesting large-print correspondence, a trusted-person arrangement or digital-support assistance may make future banking easier, but no one should be forced to disclose their PIN to a family member or stranger.
Scenario C — Huyton customer tries a sister-brand branch
A Huyton customer hears that Halifax branches can serve Lloyds customers and identifies Halifax 55 Derby Road. However, its scheduled closure is 4 November, five days before Lloyds Sherborne Square. The correct next step is not an automatic trip to that address: check the live branch finder for a still-operating branch or a cash service that handles the required transaction. This example shows why a branch-closure article should include cross-brand timelines rather than just alternative brand names.
Do FCA rules stop Lloyds from closing a branch?
No. The Financial Conduct Authority’s access-to-cash regime does not provide a general veto over commercial branch closures. The rules require designated firms to assess whether local communities will face a significant gap in access to cash—deposits and withdrawals—and to arrange reasonable replacement cash services where required. The obligation is about practical cash availability, not preserving every in-person function of the old branch. See the FCA consumer explanation and FCA guidance for firms.
The regulations have applied since September 2024. The FCA also expects firms to consider customers’ needs through its branch and ATM closure guidance. That may include notice, communication and support for people who need assistance. The existence of an FCA review does not establish that a permanent staffed replacement branch will open in every affected town.
How to request a local cash-access review or challenge an assessment
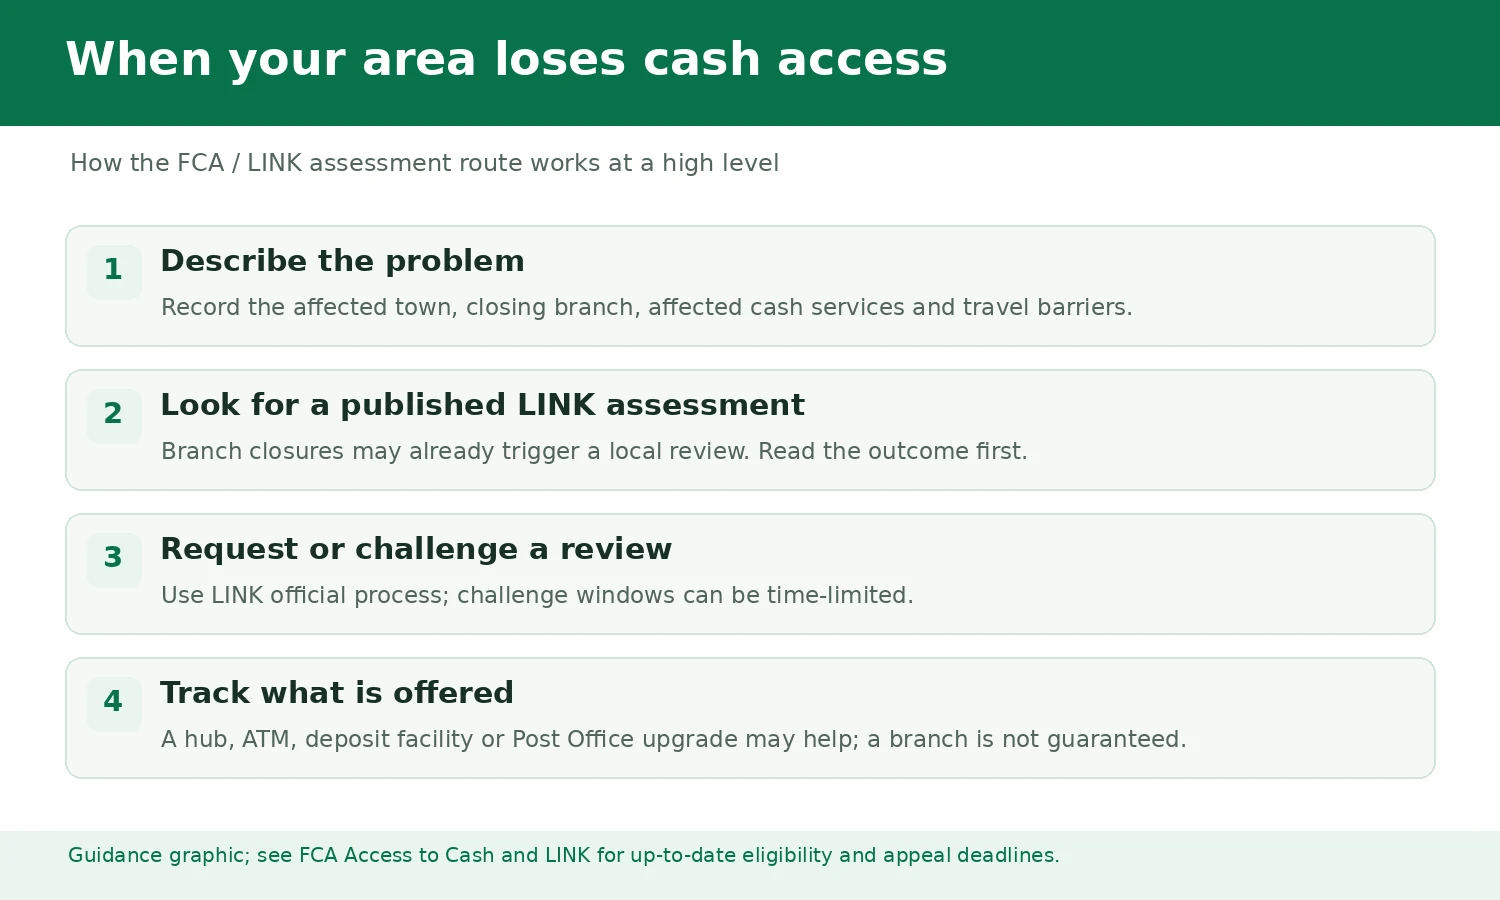
- Find the official Lloyds closure notice and check whether it mentions a LINK cash access assessment.
- Read the published local outcome and record what is missing: cash deposits, notes/coins withdrawals, free access, accessible transport or services for a specific business community.
- If the community has not been assessed, use LINK’s official request process. LINK says a closure announced in the last 12 months typically triggers a review already, unless local circumstances have significantly changed.
- If a review has been completed and you disagree, read the formal decision and challenge conditions immediately. The FCA explains that communities have 28 days to challenge an outcome.
- Support the case with evidence: trip times, bus frequency, disabilities, cash-reliant businesses, service hours and available deposit/withdrawal facilities. Avoid claims based only on nostalgia for the old premises.
Under the FCA’s account, a review ordinarily has a 12-week window, and significant cash-access gaps identified by an assessment must normally be addressed within the specified implementation timetable. Timing and exceptions matter. For the formal rules and the current mechanism, consult FCA Access to Cash and LINK’s assessment process rather than treating a media report as the appeal instructions.
The difference between an ATM, a Banking Hub and a full service branch
A cashpoint gives you cash, not staff who can discuss account restrictions or a complex probate issue. A shared Banking Hub offers a Post Office-operated counter for everyday cash services, usually during its published weekday hours. A community banker may visit once a week to help with account-specific questions, but not all banks attend every hub. A conventional bank branch can provide a wider range of staff-assisted services subject to its own facilities. These differences matter most to people who do not bank online.
Even when a new cash service satisfies an FCA assessment, customers may still lose convenient access to loan appointments, complex account questions or specialist administrative services. It is therefore more accurate to distinguish cash-access continuity from full branch-service continuity than to say a town has lost “all banking” or that a Banking Hub fully replaces every branch function.
Accessibility and digital exclusion: what customers can ask for
If a customer uses a wheelchair, has sight or hearing loss, relies on cash for budgeting, or struggles with digital services, contact Lloyds before the closure. The bank lists support such as accessible formats, talking cash machines, hearing support, assistance in branches and communication options. Different sites list facilities individually. Lloyds accessibility options are worth checking before assuming an alternative is usable.
For someone relying on a trusted helper, use the bank’s formal authority or trusted-person procedures. A helper should never ask for, keep or share someone else’s banking password, PIN or one-time security code. For a customer who cannot use the app, telephone support or a face-to-face appointment may be more appropriate than an unplanned digital transition.
What if the branch cash machine also closes?
A branch closure announcement and a cashpoint closure are related but not identical. The official Harrogate branch page says the branch is scheduled to shut on 19 November 2026, and its linked Harrogate cashpoint notice states the cash machine is also due to close permanently that day. Other towns may have independent ATM provision or free alternatives. Filter the LINK Cash Locator for free use and accessibility, and do not assume a machine shown in a cached search result will operate after a planned closure.
Do you need to switch banks? Usually not — but you may choose to
The choice depends on the services you actually need, not merely whether your nearest branded building closes. If your remaining branch, Post Office or Banking Hub is accessible and handles regular transactions, changing current accounts may add work without solving anything. If you repeatedly need a service that no nearby channel offers, compare accounts from other providers based on in-person access, business needs, fees and disability support—not just a one-off promotional switching incentive.
Check which standing orders, direct debits, salary payments, benefits, card subscriptions and business collections would be affected by any voluntary switch. For complex accounts, joint accounts, accessibility arrangements or people acting under a formal authority, confirm eligibility and the precise steps with the receiving bank before changing anything.
Practical checklist: do this before your branch closes
- Save the original branch notice, correct address and last confirmed closure date.
- Identify two alternatives—one for withdrawing cash and one for deposits or staff assistance.
- Check the new locations’ own branch closure notices: Huyton shows why this step is vital.
- Confirm cash withdrawal/deposit limits, cheque requirements, fees and exact opening hours.
- For business banking, arrange a regular takings and change-giving plan before the closing week.
- For cashpoint users, note whether the old ATM will also disappear.
- If a resident or business faces a serious local cash gap, obtain the LINK assessment or use the official challenge mechanism.
- Keep the bank’s official support contact details; do not trust unsolicited closure emails or SMS links.
Scams to avoid during a branch closure
Bank branch closures can generate confusion, which scammers can exploit by claiming customers must “verify” an account, pay a fee to keep it open, transfer funds to a supposedly safer account or hand over a card. A legitimate physical branch closure is not an instruction to move your money to an unknown account. Type the bank’s website address yourself, use a trusted bookmark or the phone number on your card, and never reveal one-time passcodes. If you receive a suspicious message, contact the bank through an independently verified channel.
Why our November list is narrower than some “full list” headlines
“Lloyds” can refer to the Lloyds Bank retail brand or to Lloyds Banking Group, which includes other brands. Published trackers can count already closed locations, future announcements, ATMs, branches, conversions and several years at once. Our list is intentionally limited to 10 Lloyds Bank branches with official page-level notices for November 2026. For other dates, brands and later changes, visit the bank’s closure-review directory and a separately dated comprehensive tracker.
This is also why we do not present the bank finder’s current number of locations as an independently audited total of open bank branches: a finder may include ATMs, hubs and future-closure locations in its result categories. Read the exact location type before interpreting any total.
Sources and editorial verification
Verified 27 October 2026, focused on November Lloyds-branded closures in the United Kingdom. Primary sources: official Lloyds branch finder and ten branch-specific listings linked in the table; Lloyds branch closure review directory; Accrington official Part 1 PDF; Lloyds Post Office banking guide; Lloyds PayPoint guide; Cash Access UK hubs; LINK Cash Locator and FCA cash-access explanation.
Editorial method: closure dates were individually cross-checked with the bank-operated pages. Typical media lists (Eastern Eye, AOL and MoneySavingExpert) were reviewed as a competitor sample, not claimed to be Google’s top three results. Unique additions include the Huyton dual-closure cross-check, analysis of Accrington’s primary-source customer-usage figures, cash-service channel-specific limits, a task-based decision table and a formal review evidence checklist. No live Google Trends search-volume figures are asserted here.
Image transparency: The cover is an illustrative generated photograph, not a photograph of an actual Lloyds branch or a real customer. The three in-article diagrams are editorial visual explainers, not screenshots from an official site. Use the linked official PDF for the authentic original Lloyds notice and its banking alternatives. No third-party screenshots have been reproduced without confirmed permission.
You may also like
 UK Guides
£100 Energy Payment: Council Tax Bands and Eligibility
Check the £100 Household Energy Payment, Council Tax bands, official postcode search and January 2027 payment arrangements in…
 UK Guides
UK Digital ID Cancelled: What Happens to Right-to-Work Checks, One Login and eVisas?
The UK cancelled its national Digital ID programme, but One Login, eVisas and right-to-work checks continue. See the…
 UK Guides
UK Student Visa Financial Requirements From 30 November 2026: New Funds and Bank Statement Rules
UK Student visa financial requirements rise on 30 November 2026: London £1,570/month, outside London £1,203/month. Learn tuition calculations,…