
2027 Tax Brackets and Standard Deduction: IRS Changes
See official 2027 federal tax brackets and standard deductions, compare 2026 amounts, and follow a worked example showing how marginal tax rates apply.
Contents
- 2027 federal income tax brackets
- Single filers and married couples filing jointly
- Heads of household and married people filing separately
- 2027 standard deduction compared with 2026
- When the basic amount is not your final deduction
- Worked example: a single filer with $70,000 of adjusted gross income
- How to use the new figures without mixing up years
- What these tables do not calculate
- Official sources and image credit
The 2027 federal income tax rates remain 10%, 12%, 22%, 24%, 32%, 35% and 37%, but the income thresholds rise. The basic standard deduction increases to $16,600 for single filers, $33,200 for married couples filing jointly and $24,925 for heads of household.
The IRS announced these figures on November 5, 2026. They apply to tax year 2027, generally reported on returns filed in 2028. If you are preparing the return normally filed in early 2027 for income earned in 2026, use the 2026 rules instead.
Below are the official ordinary-income brackets, a deduction comparison and a worked example. Figures were checked on November 6, 2026 against the IRS announcement and Revenue Procedure 2026-35. This guide covers U.S. federal individual income tax, not state tax or a complete personal tax calculation.
2027 federal income tax brackets
These thresholds apply to taxable income, not automatically to your salary or adjusted gross income. A deduction reduces the amount exposed to the brackets. A tax credit operates later in the calculation and is not interchangeable with a deduction.
Each higher rate applies only to the income within that band. For example, entering the 22% band does not make the lower layers taxable at 22%. The IRS explanation of marginal brackets describes this layered system; use the year-specific revenue procedure below for the 2027 figures.
Single filers and married couples filing jointly
| Rate | Single: taxable income | Married filing jointly: taxable income |
|---|---|---|
| 10% | Up to $12,800 | Up to $25,600 |
| 12% | Over $12,800 to $52,025 | Over $25,600 to $104,050 |
| 22% | Over $52,025 to $109,125 | Over $104,050 to $218,250 |
| 24% | Over $109,125 to $208,325 | Over $218,250 to $416,650 |
| 32% | Over $208,325 to $264,550 | Over $416,650 to $529,100 |
| 35% | Over $264,550 to $661,375 | Over $529,100 to $793,650 |
| 37% | Over $661,375 | Over $793,650 |
“Over” excludes the lower boundary; “to” includes the upper boundary. The joint-return rate schedule also applies to qualifying surviving spouses. Filing-status eligibility must be established separately; choosing the most favourable column is not an election available to everyone.
Heads of household and married people filing separately
| Rate | Head of household: taxable income | Married filing separately: taxable income |
|---|---|---|
| 10% | Up to $18,250 | Up to $12,800 |
| 12% | Over $18,250 to $69,650 | Over $12,800 to $52,025 |
| 22% | Over $69,650 to $109,100 | Over $52,025 to $109,125 |
| 24% | Over $109,100 to $208,300 | Over $109,125 to $208,325 |
| 32% | Over $208,300 to $264,550 | Over $208,325 to $264,550 |
| 35% | Over $264,550 to $661,350 | Over $264,550 to $396,825 |
| 37% | Over $661,350 | Over $396,825 |
Source for both tables: Revenue Procedure 2026-35, section 3.01. Notice that married-filing-separately thresholds do not match single thresholds throughout: the 37% band starts much earlier for separate married returns.
2027 standard deduction compared with 2026
The basic standard deduction rises for each main filing status. The following figures exclude any additional standard deduction for age or blindness and any separate deductions you might qualify for.
| Filing status | Tax year 2026 | Tax year 2027 | Increase |
|---|---|---|---|
| Single | $16,100 | $16,600 | $500 |
| Married filing separately | $16,100 | $16,600 | $500 |
| Married filing jointly or qualifying surviving spouse | $32,200 | $33,200 | $1,000 |
| Head of household | $24,150 | $24,925 | $775 |
Sources: IRS 2026 figures and Revenue Procedure 2026-35, section 3.15. A $500 larger deduction is not a $500 tax refund: it reduces taxable income by $500. Its effect depends on the rates that would otherwise apply and the rest of the return.
When the basic amount is not your final deduction
The IRS standard-deduction guide explains that eligibility and the amount can depend on age, blindness and dependent status. Some taxpayers cannot claim it, including generally a married person filing separately whose spouse itemizes, and many nonresident or dual-status aliens, subject to exceptions.
For 2027, the additional standard deduction for age or blindness is $1,700, rising to $2,100 for an unmarried individual who is not a surviving spouse. These are additional amounts under their eligibility rules, not a replacement basic deduction. Dependents also have a separate calculation. Use the relevant IRS instructions rather than automatically taking the full basic amount from the table.
The additional standard deduction for age or blindness is also distinct from the separate enhanced deduction for eligible seniors. Do not combine them under a single label or assume that every older taxpayer receives the same total.
Worked example: a single filer with $70,000 of adjusted gross income
Assume a single filer under 65 who is not blind or claimable as a dependent, has $70,000 of adjusted gross income entirely from ordinary income, takes the basic standard deduction, and has no other deductions or credits. This is a simplified rate-schedule illustration, not a completed tax return.
For 2027, taxable income is $70,000 − $16,600 = $53,400. Only the portion above $52,025 falls into the 22% band.
| Income layer | Calculation | Tax |
|---|---|---|
| First $12,800 | $12,800 × 10% | $1,280.00 |
| Next $39,225 | ($52,025 − $12,800) × 12% | $4,707.00 |
| Remaining $1,375 | ($53,400 − $52,025) × 22% | $302.50 |
| Total before credits | Sum of the three layers | $6,289.50 |
The marginal rate is 22%, but the illustrated income tax is about 9.0% of the $70,000 adjusted gross income. This excludes payroll taxes, state taxes and any other tax or credit. Calculating $53,400 × 22% would incorrectly apply the highest relevant rate to every layer.
Under the same assumptions for 2026, taxable income would be $53,900 after the $16,100 deduction. Using the 2026 rate schedules in IRS Publication 505, the calculation is $1,240 + $4,560 + $770 = $6,570. The illustrated 2027 reduction is therefore $280.50 at unchanged income. It is not a promised saving for every taxpayer.
If this example's 2027 adjusted gross income rose by another $1,000, with everything else unchanged, that extra income would stay within the 22% band and add $220 of regular federal income tax. Other real-world benefits, credits or phase-outs can change the overall result.
How to use the new figures without mixing up years
- Match the income year to the schedule. The ordinary return filed in 2027 for 2026 income uses 2026 brackets. The new 2027 figures generally concern returns filed in 2028.
- Establish your filing status. Check the actual eligibility rules before selecting a table column.
- Estimate taxable income. Start from the relevant income and adjustments, then account for applicable deductions. Do not place gross pay directly into a bracket without checking this step.
- Separate tax from withholding. The amount withheld from pay is a payment towards the eventual liability. Higher thresholds alone do not establish the size of a refund or require a W-4 change.
- Check the current IRS tools and instructions. Use the IRS Tax Withholding Estimator for the year it currently supports. Do not assume it has switched to 2027 just because the annual adjustment was announced.
For existing IRS account records, see our guide to checking your IRS online account balance and payment history. Health savings accounts have separate eligibility and contribution rules, covered in our 2027 HSA contribution-limit guide.
What these tables do not calculate
These are regular federal ordinary-income brackets. Qualified dividends and long-term capital gains can use different rate schedules. Self-employment tax, payroll taxes, state income tax, alternative minimum tax and credits require separate consideration. Someone with business income, investment gains or several interacting deductions may need a fuller calculation.
The final 2027 return instructions and tax tables should be checked when available. For returns requiring the IRS Tax Table, use that table rather than treating this educational rate-schedule example as a substitute for the prescribed filing method. Later legislation or IRS guidance can also affect an estimate.
Official sources and image credit
- IRS announcement, November 5, 2026.
- Revenue Procedure 2026-35: section 3.01 for 2027 brackets and section 3.15 for standard deductions.
- IRS 2026 tax figures and Publication 505 for the comparison.
- How federal tax brackets work and standard-deduction eligibility.
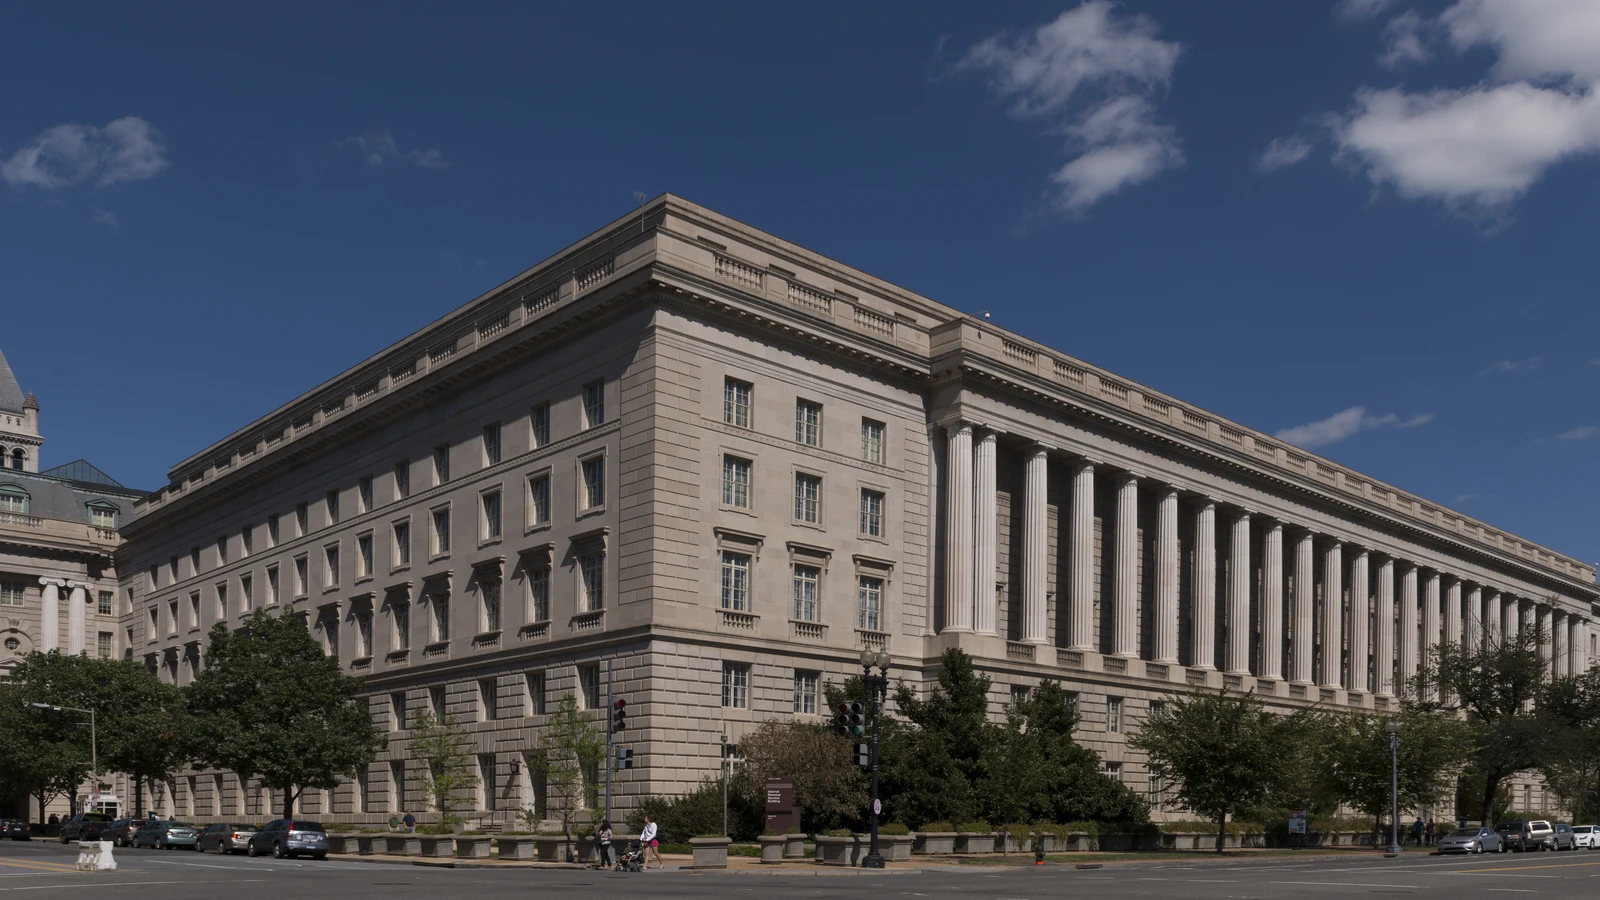
Featured photograph: the IRS building in Washington, D.C., photographed in 2012 by Carol M. Highsmith, Library of Congress collection. Public-domain image, cropped and converted to WebP. Horus Valley is an independent publisher and is not affiliated with the IRS. This article provides general information, not individual tax advice.
You may also like
 Business & Economy
TG Jones Store Closures 2026–27: Confirmed Dates, Towns and Post Office Alternatives
TG Jones closures in the UK: check announced 2026–27 shop dates, where Post Office counters are affected, and…
 Business & Economy
Making Tax Digital 2027: £30,000 Threshold, Registration, Quarterly Deadlines and Penalties
MTD Income Tax expands on 6 April 2027 for UK sole traders and landlords above £30,000 qualifying income.…
 Business & Economy
Warm Home Discount 2026–27: Who Gets the £150 Energy Bill Rebate and What to Do if It Is Missing
The £150 Warm Home Discount for 2026–27 has different eligibility routes in England, Wales and Scotland. Check dates,…